Thursday, September 14, 2006

Boundary Points

In today's blog, I define boundary points and show their relationship to open and closed sets.

Definition 1: Boundary Point

A point x is a boundary point of a set X if for all ε greater than 0, the interval (x - ε, x + ε) contains a point in X and a point in X'.

Lemma 1: A set is open when it contains none of its boundary points and it is closed when it contains all of its boundary points.

Proof:

(1) Let a,b be the boundary points for a set S of real numbers that are not part of S where a is the lower bound and b is the upper bound.

(2) If a,b are not included in S, then we have S = { x : x is greater than a and less than b } which means that x is an open set. [See Lemma 5, here]

(3) If a,b are included in S, then we have S = { x : a ≤ x ≤ b } which means that x is a closed set. [See Lemma 7, here]

QED

Lemma 2: Every real number is a boundary point of the set of rational numbers Q.

Proof:

(1) A boundary point b by definition is a point where for any positive number ε, { b - ε , b + ε } contains both an element in Q and an element in Q'.

(2) So all we need to show that { b - ε, b + ε } contains both a rational number and an irrational number.

(3) We know that this is the case based on the properties of the set of rational numbers and the properties of the set of real numbers.

We can find know that there is at least one rational number in { b - ε, b + ε } [See Corollary 2.1, here]

By the nature of the continuity of real numbers, there exists an irrational number r such that abs(b - r) is less than ε. [See here for a review of the properties of irrational numbers]

QED

References

Open Sets

Today, I talk about open and closed sets. These definitions are needed as part of the foundation of calculus. For example, I will use these properties in my future blog on compactness.

Definition 1: Open Set

A set S that is a subset of the real numbers R is open if and only if for all x ∈ S, there exists ε greater than 0 such that (x + ε, x - ε) is a subset of S.

Lemma 1: ∅ is open

Proof:

This is true since there are no elements of ∅. In other words, for all x ∈ S (none), there exists ε greater than 0 such that (x + ε, x - ε) is a subset of S.

QED

Lemma 2: The set of real numbers R is open

Proof:

(1) Let x be any real number.

(2) Let ε be any real number greater than 0.

(3) (x + ε, x - ε) is a subset of S since for all y ≤ ε, x + y and x - y ∈ R. [By the property of closure, see here for properties of real numbers]

QED

Lemma 3: The union of open sets is open

Proof:

(1) Let { Ai } be a set of open sets.

(2) Let A = ∪ { Ai }

(3) Let x be an element of A.

(4) There must exist an i such that x ∈ Ai

(5) By definition of open sets, there exists ε such that (x + ε, x - ε) is a subset of Ai

(6) But then (x + ε, x - ε) is a subset of A since Ai is a subset of A.

QED

Lemma 4: The intersection of a finite number of open sets is open.

Proof:

(1) Let { Ai } be a finite set of open sets.

(2) Let A ∩ { Ai }

(3) If A = ∅, then A is open, [See Lemma 1 above] so we can assume that A is not ∅.

(4) So there exists x such that x ∈ A

(5) for all i, x ∈ Ai.

(6) Since all Ai are open, for each Ai, there must exist an εi greater than 0, such that (x + εi, x - εi) is a subset of Ai

(7) Let ε = min({εi})

(8) Since (x + ε, x - ε) ⊂ (x + εi, x - εi) for all i, it follows that (x + ε, x - ε) ∈ A = ∩ {Ai}

QED

Lemma 5: (a,b) = { x : a is less than x is less than b } is open

Proof:

(1) Let x be any real number greater than a and less than b.

(2) Let ε = min(abs(a - x),abs(b-x))

(3) So we can see that x + ε ≤ b and a ≤ x - ε.

(4) We can further see that (x + ε/2, x - ε/2) is a subset of (a,b)

QED

Lemma 6: (a, ∞) = { x : a is less than x } is open

Proof:

(1) Let x be any real number greater than a.

(2) Let ε = abs(x - a)/2

(3) It is clear that (x - ε, x + ε) is a subset of (a, ∞)

QED

Definition 2: Complement A'

A' is the complement of A if and only if A' includes all the points that are not in A.

For example if A = negative integers, then A' = nonnegative integers.

Definition 3: Closed Set

A subset of the real numbers R is closed if its complement is open.

Lemma 7: [a,b]= { x : a ≤ x ≤ b } is closed

Proof:

(1) To prove this, we need to show that the complement of [a,b] is open.

(2) So that we have complement[a,b] = { x: x is less than a or x is greater than b }

(3) if x is less than a, then let ε = (a - x)/2. Clearly, { x - ε, x + ε } is a subset of { x : x is less than a or x is greater than b }

(4) if x is greater than b, then let ε = (x - b)/2. Clearly, { x - ε, x + ε } is a subset of { x : x is less than a or x is greater than b }

QED

Lemma 8: [a, ∞ ) = { x : x ≥ a } is closed

Proof:

(1) The complement of this is (-∞, a) = { x : x is less than a }

(2) Since x is less than a, let ε = (a - x)/2.

(3) Clearly, { x - ε, x + ε } is a subset of { x : x is less than a }

QED

References

Wednesday, September 13, 2006

Heine-Cantor Theorem

In today's blog, I will talk about uniform continuity and the Heine-Cantor theorem. I use this theorem to establish the definition of the integral.

Definition 1: Uniform Continuity

Given any positive number ε, you can find a value δ such that for all values of u,v in the interval, if absolute(u-v) is less than δ, then absolute(f(u) - f(v)) is less than ε

NOTE: This is different from the definition of continuous at a point (see Definition 1, here for definition of continuous at a point). If a function f is continuous on [a,b], then for any point u in [a,b] and for any arbitrary positive number ε, there exists a value δ greater than 0 such that if v is a number in [a,b] such that abs(u - v) is less than δ, then abs(f(u) - f(v)) is less than ε.

In the case of uniform continuity, we can find a δ which works for all points u. If a function is continuous at a point but not uniformly continuous, then there is at least one δ for a given u that is different than the other δ for the other u's.

Definition 2: Topological Space

A topological space (X,T) is a set X paired with a T which is a set of subsets of X. (X,T) must meet the following conditions;

(a) The empty set ∅ ∈ T

(b) X ∈ T

(c) The intersection of any finite number of sets in T is also in T. If (ui) is a finite set of elements in T, then ∩ui ∈ T.

(d) The union of a elements in T is also in T. If (ui) is a set of elements in T, then ∪ ui ∈ T.

In the context of a topological space, any subset of X which is an element in T is said to be an open set in relation to this topological space. Any subset of X which is not an element in T is said to be a closed set in relation to this topological space. [See Definition 1, here for definition of open set and Definition 3, here for definition of closed set]

An element of X is said to be a point.

Theorem: Heine-Cantor Theorem

Every continuous function on a compact set is uniformly continuous there

Proof:

(1) Let X,Z be metric spaces. [See Definition 2, here for definition of a metric space]

(2) Let f be a function such that f: X → Z

(3) Let us assume that f is continuous on the compact subset K of X.

(4) Let ε be a real number greater than 0.

(5) Since f is continous on K (see Definition 1, here for Definition of continuous at a point), for each x ∈ K, there exists a real δ(x) greater than 0 such that for y ∈ K:

if d(x,y) is less than δ(x), then d(f(x),f(y)) is less than ε/2.

(6) We see that the set of open balls with center x of radius δ(x)/2 cover K. [See Definition 1, here for a definition of an open ball]

(7) Using the Heine-Borel Theorem (see here), we know that there exists a finite subcovering for K such that:

K = ∪ (i=1,p) Bi where each Bi is centered at xi.

(8) Let δ be the minimum(δ(xi/2)) where i is the set of values 1, 2, ..., p.

(9) Let's assume that x,y ∈ K and d(x,y) is less than δ.

(10) Since y ∈ K and since ∪ (i=1,p) Bi is a covering for K, there exists an i such that y ∈ Bi

(11) Since the radius of each ball Bi is δ(xi)/2, we have: d(y,xi) is less than δ(xi)/2.

(12) Since d(x,y) is less than δ and δ is the minimum of all δ(xi)/2, it follows that:

d(x,y) is less than δ(xi)/2.

(13) Further, d(x,xi) less than δ(xi) since d(x,xi) ≤ d(x,y) + d(y,xi) ≤ δ(xi)/2 + δ(xi)/2 = δ(xi) [ d(x,xi) ≤ d(x,y) + d(y,xi) is true by the "triangle inequality rule" of metric spaces, see Definition 1, here]

(14) Applying the triangle inequality rule, we have:

d(f(x),f(x1)) ≤ d(f(x),f(xi)) + d(f(xi),f(y))

(15) Since d(x,xi) is less than δ(xi), we have d(f(x),f(xi)) is less than ε/2. [See step #5]

(16) Since d(xi,y) is less than δ(xi), we have d(f(xi),f(y)) is less than ε/2. [See step #5]

(17) Putting #14, #15, and #16 together gives us:

d(f(x),f(x1)) ≤ d(f(x),f(xi)) + d(f(xi),f(y)) is less than ε/2 + ε/2 = ε

(18) Thus, we have shown for every ε greater than 0, there exists a δ such that for all x,y ∈ K,:

d(x,y) is less than δ → d(f(x),f(y)) is less than ε.

QED

References

Tuesday, September 12, 2006

Introduction to integrals

If derivatives enable us to identify the slope at any point on a continuous function, integrals allow us to calculate the sum of area underneath.

In a previous blogs, I reviewed the foundations of derivatives and some of their advanced properties. In today's blog, I will examine the area under the curve problem and show how definite integrals solve this problem.

The content in today's blog is largely taken from the Wikipedia article on Riemann sums and Edwards and Penney's textbook Calculus and Analytic Geometry.

For purposes of today's blog, I will use the example of the curve f(x) = x3. I will focus on the problem of determining the area under the curve between x=0 and x=2 and y=0. The question at hand is how do we figure out a general method for determining the the total area within these constraints:
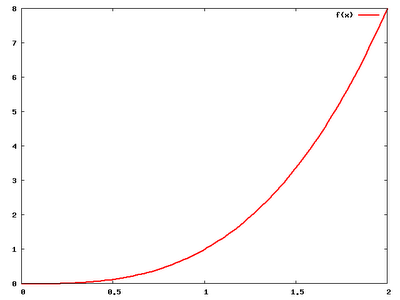
One approach to this problem to use a Riemann sum. Reimann sums were first proposed by Bernhard Riemann and today they are a major part of the foundation of calculus.

Now, let me offer a formal definition of a Riemann sum. If you are not interested in formal definitions, feel free to skip this. I will include a more intuitive summary afterwards.

Definition 1: Partition

Let I = [a,b] be a closed interval. [See Definition 3, here for definition of closed interval]

A set P is said to be a partition of I if P is a set of nonempty subintervals = { [a,x1) [x1, x2), ... , [xn-1,b] } where n, the number of subintervals, is a positive integer and a is less than x1 which is less than x2 ... which is less than xn-1 which is less than b.

Definition 2: Riemann sum

Let f(x) be a real value function on a closed interval I=[a,b] such that f: I → R. Let P be a partition of the interval I.

The Riemann sum S of f over I with respect to a partition P is:

S = ∑ (j=1,n) f(cj)(xj - xj-1)

where cj is any arbitrary point in [xj, xj-1].

If cj = the minimum in [xj, xj-1] for all j, then S is a lower Riemann sum which I will denote as L(P)

If cj = the maximum in [xj, xj-1] for all j, then S is an upper Riemann sum which I will denote as U(P).

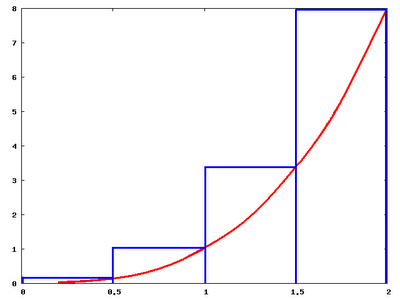
The important idea here is that a Riemann sum consists of dividing up a the graph of a function into an arbitrary number of intervals.

Here's a diagram of an upper Riemann sum U(P) where the rectangle corresponds with the maximum point in the interval.

Here is a diagram of a lower Riemann sum L(P) where the rectangle corresponds with the minimum point in the interval.
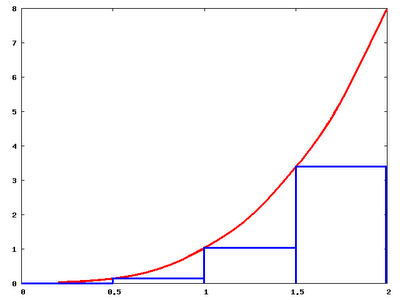
Now, it should be clear that as we increase the number of subintervals in a partition, both the L(P) and U(P) get closer to the true area under the curve. In fact, we have hit our answer when U(P) = L(P).

The goal of the rest of this blog is to demonstrate that if we continue to increase the number of subintervals, we eventually get to this point. Then, I use Riemann sums to determine the area under the curve where f(x) = x3.

Lemma 1: For any partition P of [a,b], L(P) ≤ R(P) ≤ U(P)

Proof:

(1) Let f(pj) be the minimum point in each interval [xj, xj-1]

(2) Let f(qj) be the maximum point in each interval [xj, xj-1]

(3) It follows that for all j, f(pj) ≤ f(qj).

(4) It therefore follows that for all j, f(pj)(xj - xj-1) ≤ f(qj)(xj - xj-1).

(5) And therefore that ∑ (j=1, n)f(pj)(xj - xj-1) ≤ ∑ (j=1,n)f(qj)(xj - xj-1).

(6) It follows that L(P) ≤ R(P) ≤ U(P) since for all j, f(pj) ≤ f(cj) ≤ f(qj).

(7) Applying the same steps as before (step #4 and step #5), we can conclude that:

L(P) ≤ R(P) ≤ U(P)

QED

What makes Riemann sums interesting, is that for any partition P, it is possible refine it. That is, we can increase the number of partitions and get an answer that it closer to the true area under the curve.

Definition 3: Refinement of a Partition

A partition P' is said to be a refinement of a partition P if and only if each subinterval of P' is contained in some subinterval of P.

In other words, each interval in P now corresponds to a unique set of one or more intervals in P' and the total number of intervals in P' is greater or equal to the total number of intervals in P.

Lemma 2: If P' is a refinement of P, then L(P) ≤ L(P') ≤ U(P') ≤ U(P)

Proof:

(1) From Lemma 1 above, we know that:

L(P') ≤ U(P') and L(P) ≤ U(P).

(2) Assume that a partition P' is derived from a partition P by dividing up the kth subinterval [xk-1, xk] of P into [xk-1,z] and [z, xk] by introducing a point z.

(3) From this perspective, the only difference between L(P) and L(P') is that the term f(pk)*(xk - xk-1) is now replaced by:

f(u)*(z - xk-1) + f(v)*(xk - z) where u,v are the minimum points on [xk-1,z] and [z, xk] respectively.

If we set L'(P) = L(P) - f(pk)*(xk - xk-1), then we have:

L(P) = L'(P) + f(pk)*(xk - xk-1)

L(P') = L'(P) + f(u)*(z - xk-1) + f(v)*(xk - z)

(4) Since f(pk) is the minimum point for all (xk-1, xk), we have:

f(pk) ≤ f(u)

f(pk) ≤ f(v)

(5) Hence, it follows that:

f(u)*(z - xk-1) + f(v)*(xk - z) ≥ f(pk)*(z - xk-1) + f(pk)*(xk - z) = f(pk)*(z - xk-1 + xk - z) = f(pk)*(xk - xk-1)

(6) From step #3, we have :

L'(P) + f(u)*(z - xk-1) + f(v)*(xk - z) ≥ L'(P) + f(pk)*(xk - xk-1)

So that:

L(P') ≥ L(P)

(7) We can use the same exact reasoning to establish that U(P') ≤ U(P).

(8) So that we have:

L(P) ≤ L(P') [step #6]
L(P') ≤ U(P') [Lemma 1 above]
U(P') ≤ U(P) [Step #7]

QED

Lemma 3: Limit to the lower Riemann sum

Let Pn denote a partition P of the interval [a,b] such that P consists of 2n subintervals of equal length.

Then, there exists a value I = lim (n → ∞) L(Pn)

Proof:

(1) By Definition 3 above, each Pn+1 is a refinement of Pn.

(2) Using Lemma 2 above:

L(P1) ≤ L(P2) ≤ ... ≤ L(Pn) ≤ ...

(3) The sequence { L(Pn) } is a nondecreasing monotonic sequence of real numbers. [See Definition 8, here for a definition of nondecreasing monotonic sequence]

(4) The sequence is clearly bounded since:

(a) Let D = the minimum value of f on [a,b] (See Theorem, here for proof that a minimum exists)

(b) Let U = the maximum value of f on [a,b] (See Lemma 3, here for a proof that the maximum exists)

(c) Since L(Pn) = ∑ (i = 1, 2n) f(pi)(xi - xi-1), it is clear that:

U*(b-a) ≤ L(Pn) ≤ M*(b - a)

(5) Therefore, I must exist since a bounded monotone sequence of real numbers must converge. [See Lemma 1, here]

QED

Definition 4: mesh(P)

The mesh of a partition P is the largest length of xi - xi-1.

If all the subintervals that make up the Riemann sum are the same, then mesh(P) = this value. If they are not the same, then mesh(P) = the largest subinterval.

Lemma 4:

For any given real ε greater than 0, there exists a real δ greater than 0 such that if P is a partition of [a,b] with mesh(P) less than δ and P' is a refinement of P, then:

abs(L(P) - U(P)) is less than ε/3 and abs(R(P) - R(P')) is less than ε/3

for any two Riemann sums R(P) associated with P and R(P') associated with P'.

Proof:

(1) Let f be a continous function on the closed interval [a,b]

(2) Since [a,b] is bounded and closed, [a,b] is compact. [See Heine-Borel Theorem, here]

(3) Since [a,b] is compact, f is uniformly continuous on [a,b]. [See Heine-Cantor Theorem, here]

(4) So, there exists a number δ greater than 0 such that if:

abs(u - v) is less than δ, then abs(f(u) - f(v)) is less than ε/[3(b - a)]. [See Definition 1, here for definition of uniformly continuous functions]

(5) Suppose now that P is a partion of [a,b] with mesh(P) less than δ.

(6) Then, abs(U(P) - L(P)) = ∑ (i=1,n) abs(f(qi) - f(pi))Δxi which is less than ε/[3(b-a)]∑(i=1,n) Δxi = ε/3 [Since ∑(i=1,n) Δxi= (b - a)].

This is valid since abs(pi - qi) is less than δ since mesh(P) is less than δ and pi and qi belong to the same interval.

(7) By Lemma 1 above, L(P) ≤ R(P) ≤ U(P) where R(P) = any Riemann sum and this is also true of L(P') ≤ R(P') ≤ U(P') where P' is a refinement of P.

(8) By Lemma 2 above, L(P) ≤ L(P') ≤ U(P') ≤ U(P).

(9) Combining #7 and #8, we can see that R(P) and R(P') are both within the interval [L(P), U(P)] which means that abs(R(P) - R(P')) is less than ε/3 since abs(U(P) - L(P)) is less than ε/3 [From step #6]

QED

This leads us to a definition of a definite integral.

Definition 5: Definite Integral (or Riemann Integral)

∫(a,b) f(x)dx = lim (n → ∞) ∑ (j=1,n) f(cj)(xj - xj-1)

I will try to explain each part of the definition since it is very formal. The ∫ is the notation introduced by Leibniz to indicate the sum of a continuous function (as opposed to ∑ which is the sum of a discrete set of values).

The (a,b) is the closed interval of the integral. The a should really be at the top of the ∫ and the b at the bottom but I am stuck with the limitations of html so this is the notation that I use.

dx is Leibniz's notation for Δx. The idea here is that the integral is the sum of rectangles, that is, an infinitely small width (dx) multiplied with the height f(x) as x varies from a to b.

Putting this together just says the "sum of the continuous function in the closed interval [a,b]".

So, we are defining the integral to mean the limit of the Reimann sum as the partition mesh gets closer and closer to 0.

Lemma 5: abs(a + b) ≤ abs(a) + abs(b)

Proof:

(1) if a,b are both nonegative, then abs(a + b) = a + b = abs(a) + abs(b).

(2) if both are both negative, then abs(a + b) = -(a + b) = -a + -b = abs(a) + abs(b)

(3) if a+b is positive and a is negative, then abs(a + b) = b - a is less than b + (-a) = abs(b) + abs(a) [We can make a parallel argument if a+b is positive and b is negative]

(4) if a+ b is negative and b is positive, then abs(a + b) = -(a + b) = -a -b = abs(a) - abs(b) which is less than abs(a) + abs(b). [We can make a parallel argument if a+b is negative and a is positive]

QED

Corollary 5.1: abs(a + b + ....) ≤ abs(a) + abs(b) + ...

Proof:

(1) We know that abs(a1 + a2) ≤ abs(a1) + abs(a2) from Lemma 5 above.

(2) Assume that it is true for up to some n so that we have:

abs(a1 + a2 + ... + an) ≤ abs(a1) + abs(a2) + ... + abs(an)

(3) Let b = a1 + a2 + ... + an

(4) abs(b + an+1) ≤ abs(b) + abs(an+1) [From Lemma 5 above]

(5) Replacing b with a1 + a2 + ... + an gives us:

abs(a1 + a2 + ... + an + an+1) ≤ abs(a1) + abs(a2) + ... + abs(an) + abs(an+1)

QED

Theorem: For any continuous function, the Riemann sum converges to the area under the curve.

Let I = the area under the curve. Let f be a function continuous on the closed interval [a,b]

For any positive real ε, there exists a positive real δ such that if P is a partition on f in [a,b] such that the mesh(P) is less than δ, then abs(I - R(P)) is less than ε where R(P) = the Riemann sum based on partition P.

Proof:

(1) Let ε be a real greater than 0.

(2) Let δ be a real greater than 0 based on the Lemma 4 above.

(3) By Lemma 3 above, there exists a δ2 such that there if we find an n such that mesh(Pn) is less than min(δ,δ2), then abs(L(Pn) - I) ≤ ε/3.

(4) Let P = Pn and let P' be a refinement on P.

(5) Then, abs(R(P) - R(P')) ≤ ε/3. [From Lemma 4 above]

(6) Further, since R(P') is in between L(P') and U(P') [from Lemma 1 above] and L(P) ≤ L(P') ≤ U(P') ≤ U(P) [from Lemma 2 above], it follows that:

abs(L(P) - R(P')) ≤ abs(L(P) - U(P)) ≤ ε/3 [From Lemma 4 above]

(7) abs(I - R(P)) = abs(I - L(P) + L(P) - R(P') + R(P') - R(P))

(8) Using Corollary 5.1 above, we have:

abs(I - L(P) + L(P) - R(P') + R(P') - R(P)) ≤ abs(I - L(P)) + abs(L(P) - R(P')) + abs(R(P') - R(P))

(9) Since abs(I - L(P)) is less than ε/3 [step #3 since P = Pn] and abs(L(P) - R(P')) is less than ε/3 [step #6] and abs(R(P') - R(P)) is less than ε/3 [step #5], we have:

abs(I - R(P)) is less than abs(I - L(P)) + abs(L(P) - R(P')) + abs(R(P') - R(P)) which is less than ε/3 + ε/3 + ε/3 = ε

QED

Example: Using a Riemann sum to estimate the area under f(x) = x3 on the closed interval [0,b]

(1) Using the definition of a Riemann sum, we can now use the Theorem above to get:

∫(0,b) f(x)dx = lim (n → ∞) ∑ (i=1,n) f(ci)Δx

(2) If we divide up P into n equal subintervals, then we can set Δx = b/n and set ci = ib/n. This then gives us:

∫(0,b) x3dx=lim (n → ∞) ∑ (i=1,n) (ib/n)3(b/n) = lim (n → ∞) ∑(i=1,n)(i3b4/n4)

(3) Since b,n are constants, we have:

lim (n → ∞) (i3b4/n4) = lim (n → ∞) (b4/n4) ∑(i=1,n)(i3)

(4) Using Lemma 4, here,

lim (n → ∞) (b4/n4) ∑(i=1,n)(i3) =lim (n → ∞) (b4/n4)[(1/4)n4 + (1/2)n3 + (1/4)n2]=

= lim (n → ∞) (b4)[(1/4) + (1/2)/n + (1/4)/n2]

(5) Since n is approaching ∞, this means that:

(1/2)/n and (1/4)/n2 approach 0 giving us:

lim (n → ∞) (b4)[(1/4) + (1/2)/n + (1/4)/n2] = b4/4.

This example shows the limitation of using Riemann sums to determine the integral. It makes a lot of sense as an explanation of how the integral relates to a limit. It presents problems when it comes down to applying it to a more general set of equations. If a summation formula exists, then the Riemann sum works fine. If a summation formula does not exist, then the Riemann sum, by itself, does not get us to a final result.

A much more powerful method for determining integrals is to view them as antiderivatives. That is, take the inverse of the derivative and the answer is the integral. How do we know that this works? This very important result is called the Fundamental Theorem of Calculus and I will go over its proof in my next blog.

References

Monday, September 11, 2006

Absolute value for complex powers

In today's blog, I show the details behind the following result:

if s is a complex number and a = Re(s), then abs(ns) = na

Definition 1: complex number

Any value expressible in the form a + bi where a,b are real numbers (see here for definition of real numbers) and i2=-1.

It should be pointed out that cos x + isin x fits the definition where a = cos x and b = sin x.

Definition 2: conjugate of a complex number

The conjugate of a complex number a + bi is the complex number a - bi. The conjugate of a complex number a - bi is the complex number a + bi.

If s is a complex number, its conjugate is denoted as s or as s'.

Definition 3: absolute value for complex numbers

abs(a + bi) = √a2 + b2

This definition may seem strange at first but it is a natural generalization from the concept of absolute value for real numbers. One of the key functions of an absolute value for real numbers is that it provides the distance between the two real values. For example, the distance between two real numbers x,y is abs(x - y). This is true regardless of whether x is larger or y is larger.

Subtraction is the method for distance on a line. With complex numbers, we are dealing with a plane. In this situation, distance comes from using the Pythagorean Theorem (c2 = a2 + b2) where the distance is between two (x,y) points is two absolute values abs(x1 - x2) and abs(y1 - y2). Then, the distance between the points is the triangulation of those two points which is sqrt(abs(x1 -x2)2 + abs(y1 - y2)2). [See David Joyce's article for more details]

Definition 4: Re(s)

Re(s) is the real portion of a complex number. If s is a complex number = a + bi, then Re(s)=a.

Definition 5: Im(s)

Im(s) is the imaginary portion of a complex number. If s is a complex number = a + bi, then Im(s) = b.

Lemma 1: abs(cos x + isin x) = 1

Proof:

(1) abs(cos x + isin x) = √cos2(x )+ sin2(x)

(2) Now, cos2(x) + sin2(x) = 1. [See here for details]

(3) So abs(cos x + isin x) = √1 = 1.

QED

Theorem 2: The absolute value of complex power

If s is a complex number and n a positive real and a = Re(s), then:

abs(ns) = na

Proof:

(1) There exist real numbers a,b such that s = a + bi [See definition of a complex number above]

(2) ns = na + bi = e(a + bi)ln(n) [See here for review of ln and e]

(3) e(a + bi)ln(n) = e(a)ln(n) + (bi)ln(n) = e(a)ln(n)*e(bi)ln(n) = (na)e(bi)ln(n)

(4) Using Euler's Formula,we have:

e(bi)ln(n) = cos([b]ln(n)) + isin([b]ln(n))

(5) Let's clean it up by letting x = b*ln(n) so that we have:

cos([b]ln(n)) + isin([b]ln(n)) = cos(x) + isin(x).

(6) So putting it all together, we have:

ns = (na)(cos(x) + isin(x))

(7) Since n is a positive real and a is a real, we know that abs(na) = na

So that:

abs(na)(cos(x) + isin(x))) = na*abs(cos(x) + sin(x))

(8) Using Lemma 1 above, we now have:

abs(ns) = na where a = Re(s).

QED

Lemma 3: Triangle Inequality for Complex Numbers

If s,t are complex numbers, abs(s + t) ≤ abs(s) + abs(t)

Proof:

(1) There exists a,b,c,d (see Definition of complex number above) such that:

s = a + bi
t = c + di

(2) abs(s + t) = abs((a+c) + (b+d)i = √(a+c)2 + (b+d)2 [See Definition of absolute value above for complex numbers]

(3) abs(s + t)2 = (a+c)2 + (b + d)2 = [(a + c) + (b + d)i][(a + c) - (b + d)i] = [s + t][s + t]' [See Definition 2 above for details on conjugates of complex numbers]

(4) [s + t]' = (a + c) - (b + d)i = (a - bi) + (c - di) = s' + t'

(5) abs(s + t)2 = [s + t][s' + t'] = ss' + [st' + s't] + tt'

(6) We can also see that:

ss' = (a + bi)(a - bi) = a2 + b2 = abs(s)2

tt' = (c + di)(c - di) = c2 + d2 = abs(t)2

[st' + s't] = (a + bi)(c - di) + (a - bi)(c + di) = ac - adi + bci + bd + ac + adi - bci + bd =
= 2ac + 2bd

s't = (a + bi)(c - di) = ac + bci -adi + bd

(7) So, ss' + [st' + s't] + tt' = abs(s)2 + 2Re(s't) + abs(t)2

(8) 2*abs(s't) ≥ 2Re(s't) since:

(a) abs(s't) = √[(ac + bd) + (bc - ad)i][(ac + bd) - (bc - ad)i] = √[(ac + bd)2 + (bc - ad)2

(b) ac + bd = √(ac + bd)2

(c) Since (bc - ad)2 ≥ 0, it is clear that 2*abs(s't) ≥ 2&Re(s't)

(9) So that we have:

abs(s + t)2 ≤ abs(s)2 + 2*abs(s't) + abs(t)2

(10) abs(s't) = abs(s)*abs(t) since:

abs(s)*abs(t) = √a2 + b2*√c2 + d2 = √a2c2 + a2d2 + b2c2 + b2d2

abs(s't) = √[(ac + bd)2 + (bc - ad)2 = √a2c2 + 2abcd + b2d2 + b2c2 + a2d2 - 2abcd = √a2c2 + a2d2 + b2c2 + b2d2

(11) This gives us:

abs(s + t)2 ≤ abs(s)2 + 2*abs(s)*abs(t)+ abs(t)2 = (abs(s) + abs(t))2

(12) Squaring both sides gives us:

abs(s + t) ≤ abs(s) + abs(t) since abs(s + t), (abs(s) + abs(t)) are both nonnegative.

QED

References

Saturday, September 09, 2006

Bolzano-Weierstrass Theorem

The Bolzano-Weierstrass Theorem is a very important theorem in the realm of analysis. It was first proved by Bernhard Bolzano but it became well known with the proof by Karl Weierstrass who did not know about Bolzano's proof. In light of this history, the proof gets its current name. I use it in my proof for the Cauchy Criterion which also an important theorem in analysis.

It says:

every bounded sequence has a convergent subsequence

To make heads or tails of this, it is necessary to offer some definitions of bounded sequence and convergent subsequence. Since this is one of the subtleties of analysis, I will attempt to provide a complete formal definition. Interspersed, I will provide some comments that will make the ideas clear even if you wish to skip some of the formalisms.

Let's start with sequence. This one is a tougher nut to crack, then it might seem. From one perspective, a "sequence" is just a set of numbers but from another perspective, this definition in itself is too limiting. For example, what about a sequence of points on a line?

To apply to all these domains, we will use an abstraction called a metric space and to define this, we must first define a metric.

Definition 1: metric

A metric is a binary function d(a,b) on a set X such that for any a,b,c ∈ X:

(a) d(a.b) is a real number.

(b) d(a,b) ≥ 0

(c) d(a,b) = 0 if and only if a = b

(d) d(a,b) = d(b,a)

(e) d(a,c) ≤ d(a,b) + d(b,c)

In other words, a metric is a distance function. For real numbers, the standard metric is an absolute subtraction. The distance between any two numbers x,y is abs(x - y).

Definition 2: Metric Space

A metric space is a pairing of a set X with a metric, that is, a distance function. Any element in X can be thought of as a point in the metric space.

From this perspective, all the number systems (integers, reals, rationals) are examples of metric spaces as are geometric coordinates (lines and planes).

Definition 3: Sequence

A sequence is a mapping from the set of natural numbers to the points of a given metric space.

In other words, there is a first element, a second element, a third element, etc.

For example:

the set of even numbers = {2, 4, 6, ...}

Definition 4: Bounded Sequence

A sequence an is bounded if there exists some number k such that abs(an) ≤ k for all elements in the sequence.

By this definition, a bounded sequence has both a least upper bound and a greatest lower bound.

OK, good. To continue on with formal definitions, we now need a definition of strictly increasing.

Definition 5: Strictly Increasing

A function f(x) is said to be strictly increasing if x is less than y implies f(x) is less than f(y).

I now use the definition of strictly increasing in the next definition.

Definition 6: Subsequence

If (an) is sequence, then a subsequence is (anr) where each nr is a strictly increasing sequence of natural numbers.

The main idea here is that if a sequence is a mapping of the set of natural numbers to points in a metric space. Then a subsequence is a mapping of a set of natural numbers to a subset of natural numbers to points in a metric space.

Here's an example. Let's say we have the sequence of natural numbers = (1,2,3,4,...)

In this case, we have a mapping from the set of natural numbers to the set of natural numbers. The first element is 1, the second element is 2, and so on. Remember, the set of natural numbers is a metric space, that is, they are a set combined with a distance function for any two elements from that set.

Now, let's say we have the sequence of odd numbers which is subsequence of the natural numbers so that we have (1,3,5,7,9,..)

This is a mapping from the natural numbers to the natural numbers to a metric space in the sense that the first element of the odd numbers, 1, maps to the first element of the sequence of integers which maps to 1. The second element of the odd numbers, 3, maps to the third element of the sequence of integers which maps to 3.

The main idea here is that a subsequence maintains the order of the sequence but deletes some of the elements. So, all subsequences are sequences in themselves but they also have a mapping to the elements of another sequence.

Definition 7: Convergent Sequence

A sequence (an) in the metric space (X,d(a,b)) is said to be convergent if there exists a point x ∈ X such that:

for every real number ε greater than 0, there exists a natural number N such that if n greater than N, d(an,x) is less than ε.

The notation for this is:

lim (sn) = x.

In other words, if we are talking about a sequence of real numbers where the distance function d(a,b) is just subtraction and the metric space is just the set of real numbers, then this says that for any convergent sequence, there is a limit for this sequence (which is a real number) such that we can pick a point in the sequence where all elements of the remaining elements of the sequence are arbitrarily close to the limit. In other words, the sequence is said to converge to this limit.

For the proof below, we also need:

Definition 8: Monotone Sequence

A sequence sn is monotonic if it meets one of the four following conditions:

(1) Monotonically Increasing: i greater than j → si greater than sj

(2) Monotonically Decreasing: i greater than j → si is less than sj

(3) Monotonically Nondecreasing: i greater than j → si ≥ sj

(4) Monotonically Nonincreasing: i greater than j → si ≤ sj

The main idea behind a monotone sequence is that it moves in a consistent direction. It is either gradually increasing, gradually decreasing, or just staying the same without ever regressing.

Now, with these definitions aside, we are ready to start on the proof of the Bolzano-Weierstrass Theorem. We will also need some lemmas to begin.

Lemma 1: All bounded monotone sequences converge.

Proof:

(1) Assume that S is a bounded nondecreasing sequence = s1, ..., sn. (We will be able to make an analogous argument for bounded nonincreasing sequences so we only need to prove this one case)

(2) Let b = sup S

NOTE: sup S means the supremum for the sequence S which is the least upper bound for the sequence S. We know that this exists since S is bounded.

For nonincreasing sequences, we would let b = inf(S) where inf(S) is the infimum for the sequence S which is the greatest lower bound for the sequence S.

(3) Let ε be any positive number.

(4) Then, there is some N such that sN is greater than b - ε

We know that this exists otherwise b would not be the least upper bound since b - ε is less than b. We can make an analogous argument using the greatest lower bound for a bounded nonincreasing sequence.

(5) Since S is nondecreasing, for all n ≥ N, sn is greater than b - ε. [See Definition of monotone sequence above]

(6) S is also bounded by b so we have:

b is greater than sn which is greater than b - ε

(7) But this implies that abs(sn - b) is less than ε since:

if we subtract b from all sides then we get:

0 is greater than sn - b which is greater than -ε

Since ε is greater than 0, we have:

sn - b is between -ε and +ε.

(8) So, by the definition of a convergent sequence, we have:

lim(sn) = b.

QED

Lemma 2: Every sequence has a monotonic subsequence

Proof:

(1) Let us call a term si in a sequence S dominant if it is greater than all the terms that follow it.

(2) It is clear that each sequence either has a finite number of dominant terms or an infinite number of dominant terms.

(3) Let us start by handling the case where a sequence S has an infinite number of dominant terms.

(4) We can now form a subsequence that only includes these dominant terms. [See definition of subsequence above]

(5) Then for every Snk that makes up the subsequence, Snk is greater than Snk+1 which means that the subsequence is monotonic decreasing sequence. [See definition of monotone sequence above]

(6) Now, let's handle the case where there is a finite number of dominant terms.

(7) Let's label the first term after the last dominant term (since there are only a finite number of them), n1. If there aren't any dominant terms, then let's label the first term in the sequence n1.

(8) Now since n1 is not dominant, there must be another term in the sequence which is greater than n1. We can call this next term n2. But n2 is not dominant so there must be an n3 and so on.

(9) We now have constructed a nondecreasing monotone subsequence. [See definition of monotone sequence above]

QED

Theorem: Bolzano-Weierstrass Theorem

Every bounded sequence has a convergent subsequence

Proof:

(1) Let (sn) be a bounded sequence.

(2) By Lemma 2 above, we know that it has a monotonic subsequence.

(3) By Lemma 1 above, the monotonic subsequence converges.

QED

References